When Should You Amend Taxes? Know the Signs

A missed W-2, an overlooked 1099, or a deduction entered twice can turn a completed tax return into a source of worry. The question, “when should you amend taxes,” usually comes up after you spot an error and wonder whether it will change what you owe, delay a refund, or create a problem with the IRS. The good news is that not every mistake requires an amended return. Knowing the difference can save time, stress, and unnecessary paperwork.

When Should You Amend Taxes?

You should generally amend a federal tax return when information on the original return was wrong or incomplete and the correction changes your income, deductions, credits, filing status, or tax liability. For most individual taxpayers, the correction is made with Form 1040-X, Amended U.S. Individual Income Tax Return.

Common reasons to amend include forgetting to report income from a W-2, 1099, K-1, or other tax form; claiming the wrong filing status; missing a legitimate deduction or credit; reporting the wrong number of dependents; or making an error in business income and expenses reported on your individual return.

For example, if you filed your return and later received a 1099-NEC for freelance work, your reported income is incomplete. An amended return is usually appropriate because the additional income can change your tax due, self-employment tax, and potentially other credits or deductions. Likewise, if you did not claim an eligible child care credit or education credit, amending could result in a larger refund.

An amendment can work in either direction. It may help you recover money that was left on the table, or it may correct an underpayment before penalties and interest grow. Filing promptly does not erase every consequence, but it demonstrates that you are taking steps to correct the record.

Errors That Usually Do Not Require an Amendment

A simple math error often does not require Form 1040-X. The IRS typically corrects basic calculation mistakes while processing a return. The agency may send a notice explaining the adjustment, along with any change to your refund or balance due. If you receive that notice, read it carefully before filing anything new.

You also should not amend solely because your original return is still being processed. Filing a second return or amendment before the original has been processed can create confusion and delay both filings. Wait until the IRS completes processing the original return, unless you have been directed otherwise by a tax professional or the IRS.

If the IRS adjusts your return and you agree with the change, you may not need to take further action. If you disagree, the right response may be to reply to the notice with supporting documentation rather than file an amended return. The facts and the type of notice matter.

Changes That Can Affect More Than Your Refund

Some errors seem small but can affect several parts of a return. A change in adjusted gross income, for instance, may alter eligibility for credits, retirement contribution deductions, health insurance marketplace premium tax credits, or deductions tied to income limits.

Filing status deserves particular attention. Choosing single instead of head of household, or married filing jointly instead of married filing separately, can significantly change the result. Dependency errors can have a similar effect because a dependent may be connected to child-related credits, education benefits, earned income credit eligibility, and other tax calculations.

Business owners should be especially careful with changes to business income and expenses. A corrected Schedule C may affect income tax, self-employment tax, retirement plan contribution limits, and quarterly estimated tax planning. If payroll filings are involved, the process is different. Corrections to Forms 941 or 940 generally require the applicable employment tax adjustment form, such as Form 941-X, rather than an individual Form 1040-X.

That distinction matters. An amended income tax return does not automatically correct payroll reports, W-2 information, contractor reporting, sales tax filings, or state business returns. Each filing has its own correction process and deadlines.

How Long Do You Have to Amend a Tax Return?

In many cases, taxpayers have three years from the date the original return was filed to claim an additional refund, or two years from the date the tax was paid, whichever date is later. There are exceptions, including special rules for certain bad debts, worthless securities, disaster losses, foreign tax credits, and other circumstances.

The deadline to amend is not the same as the deadline for the IRS to assess additional tax. If an amendment shows that you owe more, filing as soon as you identify the issue can reduce additional interest and penalties. Interest generally continues to accrue until the balance is paid.

State and local tax returns may also need to be amended when a federal return changes. Ohio taxpayers should not assume that correcting the federal return resolves every state or municipal obligation. A federal income adjustment can affect your Ohio return and, depending on your location and circumstances, local income tax filings as well.

What to Gather Before You File Form 1040-X

An amended return should be complete, accurate, and supported by records. Before preparing one, compare the filed return with the corrected information. Gather the missing or revised W-2s, 1099s, K-1s, receipts, account statements, mileage records, dependent documentation, and any IRS notices that relate to the change.

Form 1040-X requires you to show the original amount, the net change, and the corrected amount for relevant items. It also asks for an explanation of what changed and why. A clear explanation helps establish the purpose of the amendment and reduces the chance that the filing creates further questions.

If the change affects schedules or forms attached to the original return, include the corrected versions. For instance, a change to self-employment income may require a revised Schedule C and Schedule SE. A missed education credit could require the appropriate education credit form and proof of qualified expenses.

Keep copies of everything filed, along with proof of payment if you owe additional tax. An amended return can take time to process, so good records make it easier to respond if questions arise later.

Avoid These Common Amendment Mistakes

The biggest mistake is amending before confirming that an amendment is actually needed. Start by reviewing the original return, the new information, and any IRS correspondence. A tax software alert, a changed expectation about your refund, or a duplicate document does not automatically mean the filed return was wrong.

Another common problem is correcting one line while overlooking related changes. Tax returns are connected calculations. Adding income may affect credits, deductions, estimated tax penalties, and state returns. Claiming a dependent may affect more than one credit. A thorough review is better than a quick patch.

Do not ignore an amount due shown on the amended return. Pay as much as possible when filing, even if you cannot pay the full balance immediately. This can limit the growth of interest and penalties. If paying in full is not realistic, address the balance rather than letting it become a larger tax resolution issue.

Finally, do not amend a return merely to replace it with a different tax strategy after the fact. Some elections have specific deadlines and cannot be changed freely. The ability to amend depends on the election, the tax year, and the timing.

Get the Correction Right Before It Becomes a Larger Issue

Tax amendments are manageable when they are handled carefully, but they can become complicated when income, business records, dependents, multiple states, or IRS notices are involved. A professional review can help determine whether an amendment is necessary, identify related filings that need attention, and make sure the correction is consistent with your records.

JPC Advisers helps Cleveland-area individuals and business owners address tax filing errors with practical guidance and personalized support. If you have found a mistake after filing, acting early and correcting it accurately can bring clarity back to your finances and help you move forward with greater confidence.
Tax Relief Company Reviews: What to Look For

A tax debt notice can make a polished website or a five-star rating look more convincing than it really is. Tax relief company reviews are useful, but they should be one part of a careful decision, not the entire decision. The right provider should help you understand your IRS or state tax issue, explain your options in plain language, and set realistic expectations about cost, timing, and results.

For Cleveland taxpayers and business owners, the stakes can be significant. A tax problem may involve penalties, wage garnishment, a federal tax lien, unfiled returns, payroll tax obligations, or years of unanswered notices. Resolving it requires more than a sales promise. It requires accurate records, a sound strategy, and consistent follow-through.

How to Read Tax Relief Company Reviews

Start by looking for details rather than star ratings alone. A short review saying, “Great service,” may be encouraging, but it does not tell you whether the company handled a complex matter properly. A more useful review explains the client’s starting problem, how the firm communicated, whether fees were explained, and what work was actually completed.

Look for recurring themes across reviews. If several clients mention timely callbacks, clear explanations, and organized support, that pattern is more meaningful than one unusually glowing comment. The same is true on the negative side. Repeated concerns about surprise charges, difficulty reaching staff, or pressure to pay before receiving a clear assessment deserve attention.

Also consider the type of tax issue described. A company that routinely helps individuals with a single year of unpaid taxes may not be the best match for a business owner facing payroll tax liabilities, missing business returns, and bookkeeping problems. The best fit depends on the facts of your case.

Separate Marketing Promises From Tax Resolution Work

Some tax relief advertisements focus heavily on settling tax debt for “pennies on the dollar.” An offer in compromise can be a legitimate IRS program, but it is not available to everyone. The IRS reviews income, expenses, assets, future earning potential, and compliance history before accepting an offer. Many taxpayers will be better served by an installment agreement, penalty abatement request, currently not collectible status, or a plan to file overdue returns and become compliant.

A dependable provider should not guarantee a specific settlement before reviewing your financial information. They should explain that the first step is usually obtaining tax records, confirming the balance due, checking filing compliance, and identifying collection deadlines. This may not sound as dramatic as a quick settlement promise, but it is how responsible tax resolution begins.

Pay attention to the language used in reviews and consultations. Positive signs include statements that the firm explained multiple options, advised the client when a settlement was unlikely, or helped the client create a manageable payment plan. Honest guidance can save money and prevent additional frustration, even when the answer is not the one a taxpayer hoped to hear.

Check Who Will Handle Your Case

Tax resolution is not a one-size-fits-all service. Before hiring a provider, ask who will review your case and communicate with the IRS or state tax agency. Depending on the situation, that work may be handled by a certified public accountant, enrolled agent, tax attorney, or trained tax professional working under appropriate supervision.

Credentials matter, but accessibility matters too. You should know the name of the person responsible for your case, how to reach them, and how often you can expect updates. A large national operation may have substantial resources, but a local firm may offer more direct communication and a better understanding of your broader financial picture. Neither model is automatically better. The right choice is the one that provides qualified representation and dependable service.

Ask whether the firm can also address the conditions that created the tax problem. For example, a small business that falls behind on payroll taxes may need better payroll administration, current bookkeeping, and a process for setting aside tax funds. Resolving an old balance without correcting ongoing compliance issues can lead to another problem next year.

Questions Tax Relief Company Reviews May Not Answer

Even detailed reviews cannot answer every question about your situation. A direct conversation should fill in the gaps before you sign an agreement or pay a large upfront fee. Ask for a plain-English explanation of the scope of work, including which tax years and agencies are involved.

You should also ask how fees are structured. Some firms charge a flat fee, while others bill in stages based on the work required. A flat fee can provide predictability, but only if you understand what it covers. Find out whether the fee includes reviewing notices, preparing unfiled returns, requesting transcripts, communicating with tax agencies, negotiating a resolution, and monitoring a payment arrangement. If those services are separate, ask for an estimate of the total expected cost.

It is also reasonable to ask about timing. IRS matters often move slowly, especially when agency backlogs, missing returns, or incomplete records are involved. A provider cannot control every deadline, but they should explain what they can do promptly, what depends on the IRS, and what they need from you to keep the case moving.

Before proceeding, make sure you can answer these practical questions:

  • What specific tax problem is the firm being hired to address?
  • Which professional will manage the case and contact tax agencies?
  • What work is included in the quoted fee, and what could cost extra?
  • What documents, returns, and financial records must you provide?
  • What outcomes are realistic based on your income, assets, and filing history?

Clear answers are a sign of professionalism. Vague reassurances are not.

Watch for Warning Signs Before You Hire

A poor review is not always proof that a company is unreliable. Tax matters are stressful, and a client may be unhappy with an outcome that was required by their financial circumstances or the law. Still, certain patterns should make you pause.

Be cautious if a company guarantees a dramatic reduction before examining your records, insists that you pay immediately, or will not provide a written agreement describing its services. You should also be wary when staff members avoid discussing credentials, cannot explain the next steps, or repeatedly transfer you to a new representative.

Another concern is a provider that focuses only on debt reduction while ignoring unfiled returns and current tax compliance. The IRS generally expects taxpayers to be current on required filings before approving many resolution options. If you own a business, current payroll tax deposits and accurate reporting may be especially important. A long-term solution should bring your tax obligations under control, not simply delay them.

Choose Support That Fits Your Full Financial Needs

Tax debt rarely exists in isolation. An individual may need help organizing records, correcting prior returns, or adjusting withholding to avoid another balance due. A business owner may need monthly accounting support, payroll processing, insurance guidance, and a better cash-flow plan alongside tax resolution work.

This is where a relationship-based adviser can offer practical value. Instead of treating a notice as a single transaction, the provider can help identify what needs to change going forward. At JPC Advisers, that may include coordinating tax preparation, accounting, payroll, and resolution support so clients have a clearer path to compliance and less administrative stress.

The goal is not simply to make a notice disappear. It is to establish a workable plan, maintain accurate records, and make future filing seasons less stressful. When you review a potential provider, look for evidence that they will explain the process, respect your questions, and stay focused on a resolution that fits your actual circumstances.

A thoughtful choice now can protect more than your immediate finances. It can give you a reliable process for handling future tax responsibilities with greater confidence and control.

Payroll Services That Keep Your Business Moving

A missed payroll tax deposit or an incorrect paycheck can create more than an awkward conversation with an employee. It can lead to penalties, lost time, and avoidable stress for a business owner already managing customers, staff, and cash flow. Reliable payroll services give Cleveland businesses a practical way to pay people correctly while staying on top of the reporting and tax responsibilities that come with every pay period.

For a growing business, payroll is not simply a matter of calculating hours and issuing checks. It involves wage rules, withholding calculations, tax deposits, employee records, year-end forms, and deadlines that do not wait for a slow week. The right support brings order to those responsibilities so payroll becomes a dependable process instead of a recurring concern.

What Payroll Services Should Handle

Payroll support should reduce administrative work without taking business owners out of the loop. A provider should understand how your company pays employees, how often payroll runs, and what information you need to make confident decisions.

At a basic level, payroll processing calculates gross pay, withholds the appropriate federal, state, and local taxes, and determines net pay. Yet the work does not stop when employees are paid. Payroll records must be maintained, employer tax obligations must be tracked, and required filings must be completed accurately and on time.

A well-managed payroll process commonly includes employee onboarding information, direct deposit or check processing, wage and withholding calculations, payroll tax deposits, quarterly reporting, and year-end W-2 preparation. For businesses with contractors, it may also include organized payment records and 1099 preparation support. The exact scope depends on your workforce and how your business operates.

For example, a retail business with hourly employees may need careful tracking of hours, overtime, and schedule changes. A professional services company may have salaried staff, bonuses, commissions, and contractors. Both need accurate payroll, but their workflows and reporting needs are different. That is why a one-size-fits-all setup can create unnecessary problems.

Why Payroll Accuracy Matters to Your Business

Payroll errors affect real people. An employee who is paid late or receives the wrong amount may lose confidence in the business, even when the issue is corrected quickly. Repeated mistakes can also take attention away from customer service, hiring, and growth.

Compliance is equally important. Employers are responsible for withholding and remitting payroll taxes properly, filing required returns, and maintaining payroll documentation. Federal requirements are only part of the picture. Ohio and local tax obligations can add another layer, particularly for businesses with employees working in different municipalities or working remotely.

Small errors can compound over time. A missed withholding, incorrect employee classification, or late filing can result in notices, interest, and penalties. Fixing the issue often requires gathering records, reviewing prior payroll periods, and responding quickly to tax agencies. Prevention is usually less costly than correction.

Accurate payroll also supports better financial management. When payroll data is organized, business owners have a clearer view of labor costs, overtime trends, and the cash needed for upcoming payroll runs. That information is valuable when setting prices, preparing budgets, or deciding when to add staff.

When Outsourcing Payroll Makes Sense

Some very small businesses handle payroll internally at first. This can work when there is a stable workforce, straightforward pay structure, and someone on the team who understands the deadlines and reporting requirements. But internal payroll becomes more demanding as the business adds employees, expands locations, offers benefits, or hires contractors.

Outsourcing payroll is often a practical choice when the owner is spending too much time on calculations and paperwork, payroll taxes feel uncertain, or errors have started to occur. It can also make sense when a bookkeeper needs help with the payroll function but the business does not need a full-time payroll specialist.

The goal is not to give up control. It is to replace manual, high-risk tasks with a process that provides reliable records and clear visibility. Business owners should still review payroll reports, approve hours and compensation changes, and ask questions when something does not look right. A good provider makes those reviews easier, not harder.

Cost is an understandable consideration. Payroll services create an ongoing expense, but internal payroll has costs too: staff time, software subscriptions, training, corrections, and potential penalties. The best choice depends on the complexity of your payroll and the value of having experienced support available when questions arise.

Choosing Payroll Services for a Cleveland Business

A payroll provider should be more than a system that produces pay stubs. Look for a partner that can explain the process in plain language and respond when an employee change, tax notice, or reporting question needs attention.

Start by considering the service level your business needs. Some companies only need payroll calculations and direct deposit. Others need help with new-hire setup, tax filings, payroll reports, workers’ compensation information, or coordination with bookkeeping and tax preparation. Understanding those needs upfront helps prevent gaps later.

Ask how payroll information will be collected and approved, who is responsible for tax filings and deposits, and what reports you will receive. It is also wise to clarify how corrections are handled. A provider should have a clear process for addressing an incorrect paycheck, a changed tax form, or a filing issue without leaving you to sort it out alone.

Local knowledge can be especially useful for businesses in Cleveland and surrounding communities. A provider familiar with the area understands that local tax considerations may matter and can offer more direct, personalized guidance than a distant call center. When payroll, bookkeeping, tax preparation, and insurance needs overlap, working with one advisory relationship can also reduce duplicate work and inconsistent records.

JPC Advisers helps businesses bring these financial responsibilities together with practical, personalized support. Coordinating payroll with accounting and tax planning can make it easier to keep records accurate throughout the year rather than rushing to organize information at filing time.

Keep Payroll Connected to Your Books

Payroll should not operate separately from the rest of your financial records. Every payroll run affects wages, payroll taxes, benefit expenses, liabilities, and cash flow. When those entries are not recorded properly, financial statements can become misleading.

This is where coordination between payroll and bookkeeping matters. If payroll reports are reviewed regularly and reflected accurately in the books, owners can see a more realistic picture of profitability. They can also identify unusual labor costs earlier, before they become a larger problem.

A connected process is particularly helpful during tax season. Organized payroll records support accurate business returns and reduce the scramble to locate wage totals, tax payments, and year-end forms. It also creates a stronger foundation if a tax agency asks for documentation.

Businesses should keep payroll records secure and accessible. Employee Social Security numbers, bank details, addresses, and compensation data require careful handling. The process should include appropriate controls over who can submit changes, approve payroll, and access sensitive reports.

A More Reliable Way to Pay Your Team

Employees should be able to trust that they will be paid correctly and on schedule. Owners should be able to trust that payroll taxes and reporting are being handled with the same care. That confidence frees up time and attention for the work that actually moves a business forward.

If payroll has become a monthly source of uncertainty, the answer may not be more paperwork or another rushed spreadsheet check. A dependable process, supported by people who understand your business, can turn payroll into one less item competing for your attention. The next pay period is a good time to make that process easier to manage.

Financial Planning Small Businesses JPC Advisers Tailored Help

How JPC Advisers Inc. Helps Small Businesses with Tailored Financial Planning

financial planning small businesses JPC Advisers

Financial planning small businesses JPC Advisers provides involves crafting detailed, customized financial strategies that address the unique challenges and goals of each small business owner. Small businesses often face fluctuating cash flows, tax complexities, and investment decisions that require expert guidance tailored to their specific circumstances and local market conditions. At JPC Advisers Inc., we focus on delivering practical, actionable financial plans that help businesses maintain stability, optimize resources, and position themselves for sustainable growth.

Three things to know before you go further:

  • Small business financial needs are highly individualized: Factors such as industry, business size, revenue cycles, and owner goals all influence the planning approach.
  • Local economic and regulatory environments matter: Understanding regional tax codes, market trends, and economic conditions is critical for relevant advice.
  • Financial planning is a dynamic process: Plans require regular review and adjustment to stay aligned with evolving business realities and objectives.

Key takeaways

This article outlines how JPC Advisers Inc. delivers tailored financial planning services for small businesses, detailing preparation, step-by-step processes, success indicators, and when professional involvement is essential.

Point Details
Customized strategies Financial plans are developed to reflect each small business’s unique financial profile and objectives, ensuring relevance and practicality.
Local expertise Deep knowledge of local tax laws and economic conditions enables precise, compliant financial advice.
Continuous monitoring Regular plan reviews allow adjustments to changing business environments and goals, maintaining effectiveness.
Practical implementation Guidance includes cash flow management, tax consulting, investment advice, and business valuation tailored to client needs.
Jpcadvisersinc services We provide comprehensive financial planning, investment advice, tax consulting, and business valuation specifically designed for small businesses.

Preparing for tailored financial planning: What small businesses should gather and verify

Preparing for tailored financial planning: What small businesses should gather and verify - financial planning small bus

Effective financial planning begins with thorough preparation. Small business owners should collect detailed financial records and clarify their business objectives before engaging with JPC Advisers Inc. This preparation enables our team to analyze your situation accurately and develop a plan that addresses your specific needs.

Essential documents and information to assemble

  • Financial statements: Up-to-date balance sheets, income statements, and cash flow statements from the past 12 to 24 months provide insight into your business’s financial health and trends.
  • Tax returns: Business tax filings for the last two to three years help identify tax liabilities, deductions, and potential areas for optimization.
  • Debt schedules: Detailed information on outstanding loans, including principal amounts, interest rates, payment schedules, and covenants, allows us to assess liabilities and refinancing opportunities.
  • Business plans and forecasts: Existing strategic plans, sales projections, and budget forecasts inform goal-setting and resource allocation.
  • Investment portfolios: Documentation of current investments, retirement accounts, or other financial assets helps integrate personal and business financial planning.

Clarifying business goals and challenges

Before planning begins, clearly defining your business goals and challenges is critical. Consider questions such as:

  • What are your short-term and long-term growth objectives? For example, expanding product lines, entering new markets, or increasing profitability.
  • Are there seasonal or cyclical cash flow fluctuations? Understanding timing helps in managing liquidity.
  • What are your current tax challenges? Identifying areas where tax planning can reduce liabilities.
  • Do you have succession or exit plans? Planning for ownership transition or sale requires early financial preparation.

Verifying provider credentials and compatibility

Selecting the right financial consultant is essential. Small businesses should:

  • Confirm local and industry expertise: Ensure the adviser is familiar with your business sector and local tax regulations.
  • Assess the range of services offered: Confirm that the provider offers comprehensive financial planning, including tax consulting and business valuation.
  • Understand the planning process: Request a clear explanation of how financial plans are developed, implemented, and monitored.

Pro Tip: Prepare a detailed list of your business’s financial strengths, weaknesses, opportunities, and threats (SWOT analysis) to share with your adviser. This facilitates focused and effective planning discussions.

The step-by-step playbook for financial planning with JPC Advisers

The step-by-step playbook for financial planning with JPC Advisers - financial planning small businesses JPC Advisers

Our financial planning process is designed to be collaborative, thorough, and tailored to your business’s unique needs. Here’s how we work with you:

  1. Initial assessment and discovery

We conduct an in-depth review of your financial documents and discuss your business’s current financial position, operational challenges, and future aspirations. This includes analyzing cash flow cycles, profit margins, debt obligations, and investment preferences.

  1. Risk analysis and opportunity identification

Our team evaluates financial risks such as exposure to debt, market volatility, and operational inefficiencies. We also identify opportunities for tax savings, investment growth, and cost reduction strategies.

  1. Customized financial plan development

Based on the assessment, we develop a detailed financial plan that includes budgeting recommendations, investment strategies aligned with your risk tolerance, tax planning measures, and business valuation insights.

  1. Implementation guidance and coordination

We assist you in executing the plan by coordinating with your accountants, bankers, and legal advisors to ensure all elements are aligned and effectively implemented.

  1. Ongoing monitoring and plan adjustment

Financial planning is not static. We schedule regular reviews, typically quarterly or biannually, to evaluate progress, update forecasts, and adjust strategies in response to changes in your business environment or goals.

Pro Tip: Keep detailed records of financial transactions and operational changes throughout the year. This data supports accurate monitoring and timely adjustments during plan reviews.

Ready to develop a financial plan tailored specifically to your small business? Connect with JPC Advisers Inc. today to start your personalized consultation.

Recognizing success and knowing when to seek expert intervention

Recognizing success and knowing when to seek expert intervention - financial planning small businesses JPC Advisers

Measuring the effectiveness of your financial plan is essential to ensure it meets your business needs. Key indicators of success include improved cash flow stability, optimized tax payments, and tangible progress toward growth objectives.

Indicators that your financial plan is working

  • Consistent positive cash flow: Your business maintains liquidity aligned with projections, enabling timely payments and investment.
  • Tax efficiency improvements: You realize reductions in tax liabilities through strategic planning and compliance.
  • Investment performance: Your investment portfolio meets expected returns and supports business goals.
  • Business valuation growth: The assessed value of your business increases, reflecting operational improvements and market positioning.

When to involve a financial professional

Engage JPC Advisers if you experience:

  • Unexpected cash flow shortages or debt challenges: Sudden liquidity issues require expert analysis and corrective strategies.
  • Complex tax situations or regulatory changes: New tax laws or business restructuring necessitate professional guidance.
  • Capital needs for expansion: Planning for financing growth or acquisitions benefits from expert advice.
  • Succession or exit planning: Preparing for ownership transition demands careful financial and legal coordination.

Pro Tip: Schedule financial plan reviews more frequently during periods of rapid change or uncertainty to maintain alignment with your business’s evolving needs.

FAQ about financial planning for small businesses with JPC Advisers

What distinguishes financial planning for small businesses from larger corporations?

Small businesses typically have more limited financial resources, less diversified revenue streams, and closer owner involvement in daily operations. This requires financial plans that emphasize cash flow management, tax efficiency, and flexibility to adapt quickly to market changes. Unlike larger corporations, small businesses often need plans that integrate personal and business finances closely.

How does JPC Advisers integrate tax consulting into financial planning?

Tax consulting is a core component of our financial planning process. We analyze your business structure, expense classifications, and income timing to identify deductions, credits, and deferral opportunities. Our approach ensures compliance with local tax laws while minimizing liabilities. For example, we may recommend changes in expense timing or asset depreciation methods to optimize tax outcomes.

Can JPC Advisers provide investment advice tailored to small business owners?

Absolutely. We assess your risk tolerance, time horizon, and financial goals to recommend investment strategies that complement your business’s financial plan. This includes diversification across asset classes, balancing liquidity needs with growth potential, and integrating personal retirement planning with business finances.

What does business valuation involve, and why is it important?

Business valuation is a comprehensive assessment of your company’s worth based on financial performance, asset values, market conditions, and growth prospects. It is vital for sale negotiations, succession planning, securing financing, or strategic decision-making. Our valuations use industry-standard methodologies tailored to your business specifics.

How frequently should small businesses review their financial plans?

We recommend at least an annual comprehensive review, with quarterly or biannual check-ins during periods of significant change. Frequent reviews help identify deviations from the plan early, allowing timely adjustments. For example, if unexpected expenses arise or market conditions shift, revisiting the plan ensures continued relevance.

What should I expect during my first consultation with JPC Advisers?

Your initial meeting will involve a detailed discussion of your business’s financial history, current challenges, and future goals. We will explain our financial planning process, outline required documentation, and set expectations for collaboration. This session establishes a foundation for developing a customized financial plan that aligns with your business’s unique needs.

How Jpcadvisersinc helps you achieve tailored financial planning for your small business

Jpcadvisersinc specializes in providing comprehensive financial planning services that address the specific needs of small businesses. Our expertise spans financial planning, investment advice, tax consulting, and business valuation, all integrated to support your business’s financial health and growth.

We provide:

  • Comprehensive financial planning: Tailored strategies that reflect your business’s unique financial landscape and goals.
  • Investment advice: Personalized guidance on asset allocation and risk management aligned with your objectives.
  • Tax consulting: Proactive strategies to minimize tax liabilities while ensuring full compliance with local regulations.
  • Business valuation: Accurate assessments that inform strategic decisions such as sales, mergers, or succession.

Ready to secure your business’s financial future with expert guidance? Reach out to JPC Advisers Inc. now and take the first step toward tailored financial planning.

Final thoughts

Financial planning small businesses JPC Advisers offers is a highly personalized service that requires deep understanding of your business’s financial realities and goals, combined with local market knowledge and ongoing support. The most important next step is to gather your financial documents and schedule a consultation with JPC Advisers Inc. to begin developing a plan that works specifically for your business.

Partnering with a trusted financial adviser ensures you navigate complex financial challenges with confidence and position your business for long-term success.

Taking this step means you have a dedicated partner committed to your business’s financial well-being and growth.

Related reading

This article is general information, not a substitute for advice from a qualified professional. Consult a qualified professional about your own circumstances before acting on anything here.

What Insurance Does a Small Business Need?

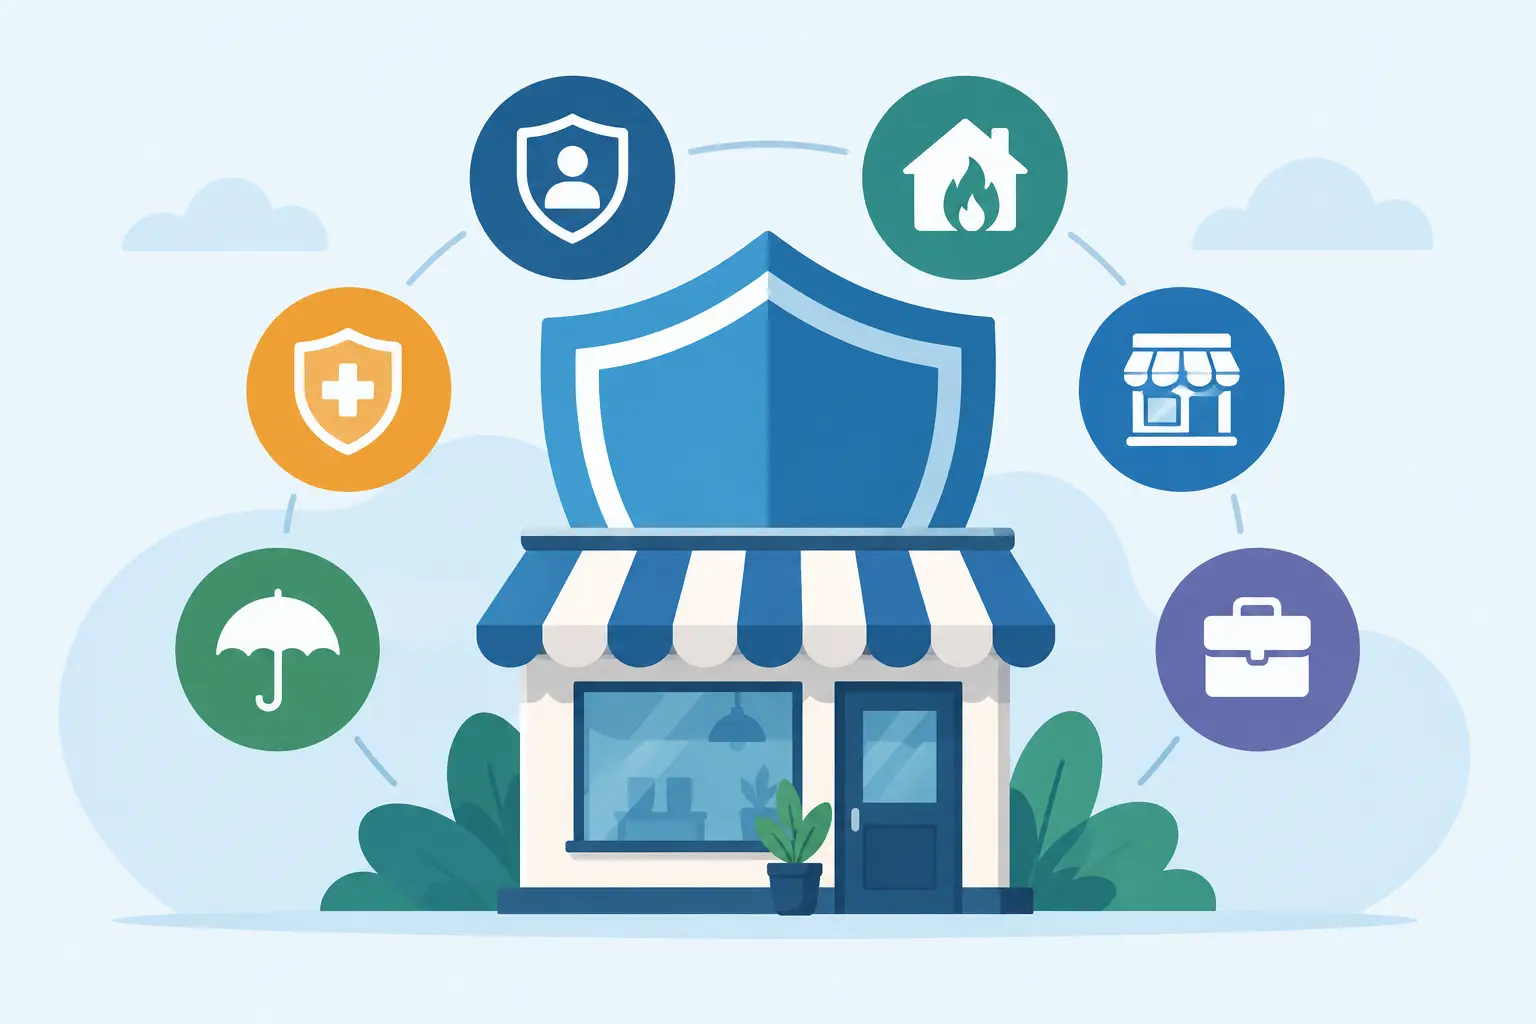
A customer slips at your location. A work vehicle is involved in an accident. A laptop containing client information is stolen. For a small business, one unexpected event can quickly become a costly interruption. That is why asking what insurance does a small business need is not just a compliance question. It is a practical step toward protecting the operation, income, and reputation you have worked hard to build.

The right coverage depends on your industry, property, employees, contracts, and risk exposure. A restaurant, contractor, consultant, retailer, and online seller do not face the same liabilities. Still, most Cleveland-area small businesses benefit from starting with a core set of protections and then tailoring coverage to how they actually operate.

What Insurance Does a Small Business Need First?

For many businesses, general liability insurance is the starting point. It can help cover claims involving third-party bodily injury, property damage, and certain advertising injuries. If a customer is hurt at your office or a contractor damages a client’s property, general liability may help with legal defense costs and covered damages.

General liability is valuable, but it does not cover every risk. It generally will not pay for damage to your own business property, injuries to employees, professional mistakes, or losses from a cyber incident. Think of it as a foundation, not a complete insurance plan.

A business owner’s policy, often called a BOP, may be a practical next step for eligible small businesses. It typically bundles general liability with commercial property coverage at a cost that can be more manageable than purchasing each policy separately. A BOP can help protect equipment, inventory, furniture, and other physical assets if they are damaged by a covered event such as fire, theft, or certain weather-related losses.

Eligibility and policy terms vary. A home-based consultant may need a different property limit than a retail shop with inventory, while a business with a high-risk operation may need separate policies rather than a standard package.

Coverage That Often Becomes Essential as You Grow

The moment you hire employees, sign larger contracts, drive for work, or store customer data, your insurance needs usually expand. The following coverages are common because they address risks that general liability and property insurance do not.

Workers’ compensation for employees

Ohio businesses with employees generally need workers’ compensation coverage. In Ohio, workers’ compensation is handled through the Ohio Bureau of Workers’ Compensation rather than a typical private insurance carrier arrangement. This coverage can help provide benefits when an employee experiences a work-related injury or illness.

Payroll accuracy matters here. Job classifications, employee status, and wage reporting can affect your workers’ compensation obligations and costs. Misclassifying a worker or reporting incomplete payroll information can create compliance problems and unexpected expense. Business owners should review these details before payroll is processed, not after a claim or audit occurs.

Professional liability for advice and services

Professional liability insurance, also known as errors and omissions coverage, is especially important for businesses that provide advice, expertise, designs, recommendations, or professional services. Examples include consultants, tax professionals, accountants, real estate professionals, technology providers, marketing agencies, and certain health or wellness businesses.

A client may claim that your work contained an error, missed a deadline, or failed to deliver the promised result. Even if the claim is not justified, defending it can be expensive. Professional liability coverage may help with legal costs and covered claims related to your services.

General liability and professional liability are often confused. General liability is commonly associated with physical injuries or property damage. Professional liability addresses financial harm that a client alleges resulted from your professional work.

Commercial auto for business driving

If a vehicle is titled to the business, commercial auto coverage is usually necessary. It can also be important when employees regularly drive personal vehicles for deliveries, client visits, errands, or job-site travel. Personal auto policies may exclude or limit business use, especially when driving is central to the work.

A contractor hauling tools, a catering company making deliveries, and a sales team traveling to client meetings each have different exposures. Be clear about who drives, what they drive, how often they drive, and whether vehicles carry equipment or products. These details affect the coverage and limits you may need.

Cyber liability for digital risk

Small businesses are frequent targets for phishing, ransomware, fraudulent payment requests, and data theft. Cyber liability insurance can help with certain costs tied to a cyber event, including data recovery, notification requirements, legal support, credit monitoring, and business interruption, depending on the policy.

This coverage is worth considering even if your business does not consider itself a technology company. If you maintain customer names, addresses, payment information, tax documents, employee records, or login credentials, you have information that needs protection. Strong passwords, multifactor authentication, employee training, and secure backups remain essential because insurance does not replace sensible safeguards.

Additional Coverage to Consider Based on Your Business

Some policies are not needed by every company, but they become important in the right circumstances. Employment practices liability insurance may help with claims involving wrongful termination, discrimination, harassment, or other employment-related allegations. As a team grows, this protection deserves a closer look.

Commercial umbrella liability insurance provides an additional layer of liability protection above qualifying underlying policies, such as general liability or commercial auto. It can make sense for businesses with substantial assets, customer traffic, company vehicles, larger contracts, or higher potential liability exposure.

Business interruption coverage can help replace lost income and assist with certain continuing expenses when a covered property loss forces the business to pause operations. This can be especially meaningful for a storefront, restaurant, salon, or manufacturer that cannot simply move work online after a fire or major property loss.

For owners whose business relies heavily on one person, key person life insurance may also be worth discussing. It can provide funds to help the company manage a major transition if a critical owner or employee dies. This is different from personal life insurance because the business is protecting its own continuity.

How to Choose Limits Without Paying for the Wrong Coverage

The lowest premium is not always the lowest cost. A policy with a small limit, large deductible, or major exclusion may leave a business responsible for the very loss it expected insurance to cover. At the same time, paying for coverage that does not match your actual operations wastes money that could support payroll, inventory, or growth.

Start by identifying the risks that could seriously disrupt the business. Consider the value of your property and equipment, the number of employees, the information you store, the vehicles you use, and the promises you make in client contracts. A landlord, lender, vendor, or client may require specific coverage types and minimum limits before you can lease space, accept a project, or bid on work.

Read the policy details, not only the coverage name. Ask about exclusions, deductibles, policy limits, covered locations, additional insured requirements, and whether legal defense costs reduce the amount available to pay a claim. If your business changes, your policy should change too. Hiring employees, buying equipment, launching delivery service, moving locations, or adding online payment processing can all create new exposures.

Keep Insurance Connected to Your Financial Operations

Insurance works best when it is part of an organized financial plan rather than a document filed away after purchase. Accurate bookkeeping helps you understand the value of business property, revenue, payroll, and potential interruption losses. Clean payroll records support workers’ compensation reporting. Good contracts clarify insurance requirements before a dispute arises.

At JPC Advisers, small business owners can coordinate insurance needs with payroll, accounting, and tax support through one practical advisory relationship. That coordination can reduce administrative stress and help ensure that operational details are not overlooked.

Review your coverage at least once a year and whenever your business takes on a meaningful change. The goal is not to insure against every possibility. It is to make sure one unexpected event does not take away the business you are working to grow.